Waiting for a seasonal discount can improve your negotiating position, but it can also leave you with fewer suitable vehicles. The cheapest-looking car may have hidden damage, deferred maintenance, an unpopular specification, or financing costs that erase the advertised saving.
The strongest buying moment is a window rather than a date. Several comparable cars should be available, your financing should be understood or preapproved, and an independent mechanic should be ready to inspect the vehicle before you negotiate. Calendar timing can help, but condition and the full transaction cost carry more weight.
- The Best Time Is a Buying Window, Not a Calendar Date
- When Different Timing Windows Help—and When They Do Not
- How to Tell a Real Bargain From a Cheaper Problem
- The Inspection and Paperwork That Matter More Than Timing
- Finance the Total Cost, Not the Monthly Payment
- A Safer Decision Process for Any Buying Window
- Frequently asked questions
- What is the $3,000 rule for cars?
- What is the cheapest month to buy a used car?
- What is the 20% rule when buying a car?
The Best Time Is a Buying Window, Not a Calendar Date
There is no guaranteed ideal week to buy a used car. End-of-month and end-of-year sales targets may improve a dealer’s willingness to negotiate, while higher inventory can give you more alternatives. Neither condition guarantees that a particular vehicle is fairly priced or mechanically sound.
September 2026 illustrates why market signals need careful interpretation. The average U. S. used-car listing price was $27,235, nearly 6% higher year over year. At the same time, used-car sales declined from August, while inventory and days to sale increased.
That combination may create more room to compare vehicles and negotiate, but it does not mean every listing became cheaper. Wholesale used-car prices were down 1.1% from August after adjustment for seasonality, vehicle age, mileage, and sample composition. Wholesale movement can influence retail pricing, but it does not determine the value of one car on one dealer’s lot.
Your decision should therefore start with the vehicle rather than the calendar. A well-maintained car with a documented history, a realistic out-the-door price, and a clean inspection can be a better purchase today than a questionable car offered during a supposedly favorable week.
When Different Timing Windows Help—and When They Do Not
Each timing window can change leverage or selection, yet none is universally cheapest. Compare equivalent vehicles and treat any seasonal pattern as a reason to investigate rather than proof of a bargain.
| Buying window | Possible advantage | Selection trade-off | Main risk |
|---|---|---|---|
| Late month or late year | Sales targets may improve negotiating leverage. | A specific desirable vehicle may sell before the deadline. | Urgency can lead you to overlook condition, fees, or inspection results. |
| Fall inventory growth | More vehicles may make comparison and negotiation easier. | Inventory may include unpopular specifications or weaker examples. | A seasonal price decline may reflect a poorer mix of vehicles rather than a discount on comparable cars. |
| Weather-related seasonal demand | Demand may soften for some vehicle types during part of the year. | Seasonality differs among convertibles, sports cars, four-wheel-drive vehicles, and economical cars. | Assuming every model follows the same pattern can produce a false bargain. |
| Any time a well-documented vehicle appears | You can secure a strong example before it attracts competing buyers. | There may be less calendar-based leverage. | Paying quickly without comparing total costs or completing an inspection. |
How to Tell a Real Bargain From a Cheaper Problem
Price comparisons are useful only when the vehicles are genuinely comparable. Match age, mileage, engine, drivetrain, trim, equipment, condition, and history before deciding that one listing is cheaper. A lower price may reflect fewer features, more wear, a less desirable configuration, or a documented problem.
Time on the lot is a clue, not a verdict. A vehicle that has been listed for a long period may have defects, an unpopular specification, an inflated price, or an unfavorable history. It may also be priced competitively but overlooked for ordinary reasons, so the next step is inspection and documentation rather than an automatic demand for a discount.
The advertised price may exclude dealer fees, preparation charges, warranties, or other add-ons. Request a written out-the-door breakdown before comparing offers. This prevents a seasonal markdown from being offset by charges that were absent from the headline price.
Immediate ownership costs can erase a small saving. Tires, brakes, scheduled maintenance, registration, and needed repairs should be estimated before you negotiate. A car with a slightly higher purchase price may be the better deal if it needs substantially less work after delivery.
The Inspection and Paperwork That Matter More Than Timing
A VIN or vehicle-history report is a screening tool, not a mechanical guarantee. It can reveal recorded ownership, title, accident, or service information, but it may miss hidden frame damage, flood damage, recent accidents, private repairs, or a mileage concern that has not entered the available records.
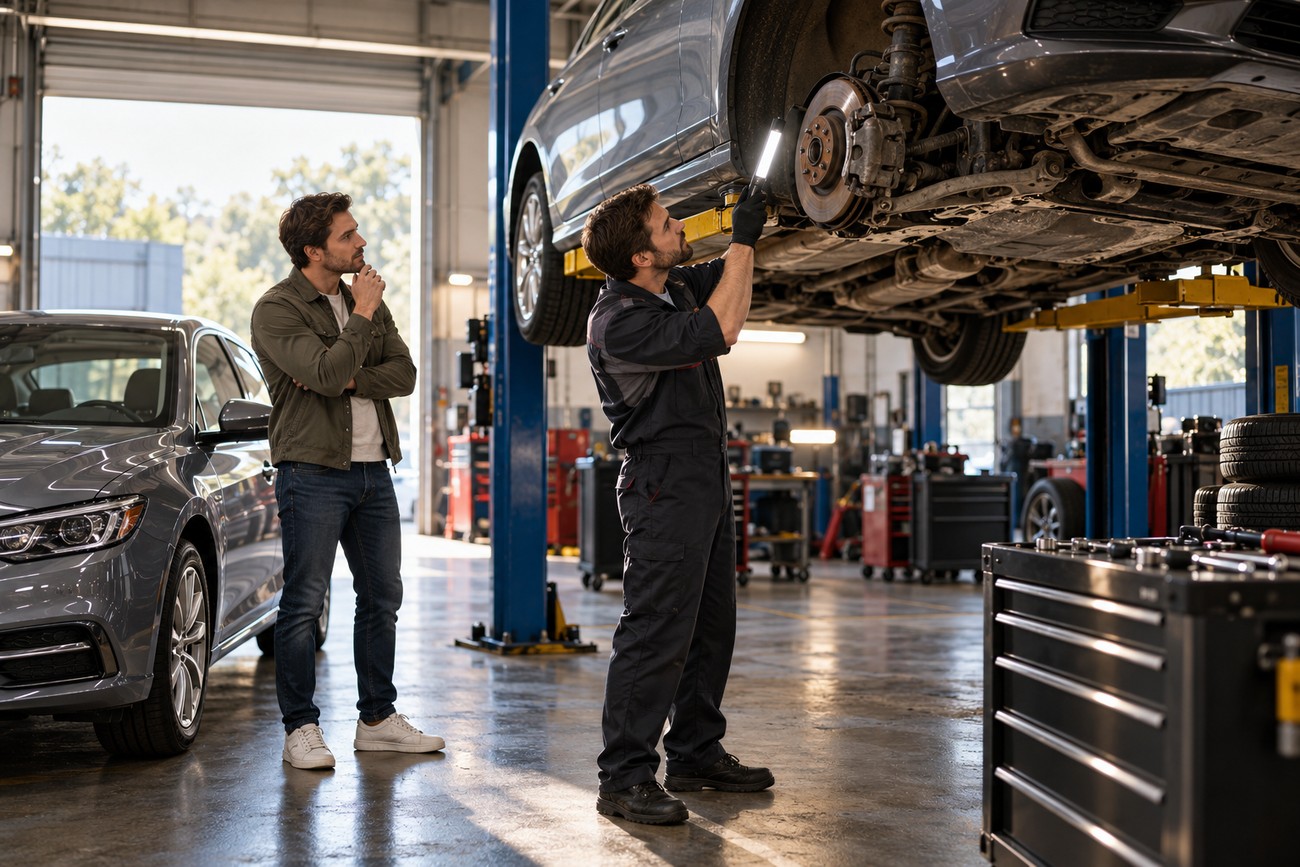
The report may also say little about the vehicle’s present condition. An independent inspection should assess the engine, transmission, suspension, tires, brakes, frame, electronics, and signs of water intrusion. Arrange that inspection before negotiating the final price, because a low offer based on an assumed repair is weaker than one supported by documented findings.
Seller resistance to a buyer-selected independent inspection is a deal-breaking signal, even when the history report is clean or the vehicle is described as certified.
Federal Trade Commission rules require dealers to display a Buyers Guide on every used vehicle offered for sale and provide it to the buyer after the transaction. Read whether the vehicle is sold as is or with limited warranty coverage, and check which systems, exclusions, and responsibilities the document describes.
Put important promises in writing. Statements about repairs, warranty coverage, included equipment, or paid fees should appear in the contract or another signed document. A verbal assurance cannot reliably protect you if the Buyers Guide and purchase agreement say something different.
Finance the Total Cost, Not the Monthly Payment
A low monthly payment can conceal a higher APR, a longer repayment period, additional fees, and greater total interest. The payment is only one part of the transaction and should not be the figure used to compare vehicles or lenders.
Calculate the full transaction cost and the full cost of credit, including the down payment, APR, loan term, interest, taxes, fees, add-ons, and total amount paid. Used cars typically carry higher interest rates and shorter loan terms than new cars, so the financing difference can materially change the cost of an otherwise similar purchase.
Compare multiple lenders before visiting or finalizing the deal. Dealer-arranged financing can be one offer among several rather than the default. A preapproval also helps you separate the vehicle’s price from the financing terms and exposes whether the dealer is presenting a genuinely competitive APR.
Keep the vehicle price, trade-in value, down payment, financing, and optional products separate during negotiations. Combining them into one monthly payment makes it harder to identify inflated fees or a costly add-on that has been folded into the loan.
A Safer Decision Process for Any Buying Window
Begin with several comparable cars rather than one tempting listing. Record each vehicle’s age, mileage, engine, drivetrain, equipment, history, advertised price, and estimated immediate maintenance. This gives you a reference point if a seller claims that a discount is exceptional.
Obtain financing approval and understand your maximum total cost before negotiating. Then collect the VIN and as reported by working professionals in the field you choose.
Complete the inspection before making your final offer. Use documented repair needs, realistic registration costs, taxes, dealer fees, and financing charges to calculate the out-the-door amount. If the seller changes the terms, refuses records, or pressures you to skip the inspection, pause the transaction.
The practical walk-away test is simple: proceed only when the seller is transparent, the vehicle’s condition is acceptable, and the total cost fits your plan. If any of those elements depends on urgency or an undocumented promise, the calendar is not giving you a good buying window.
Frequently asked questions
Timing rules can be useful as prompts for comparison, but they are not substitutes for inspection, financing analysis, or contract review. A market pattern that helps one buyer may offer little value for a different model, region, or condition.
The following questions address common rules of thumb. Each should be treated as a budgeting or research aid rather than as a guarantee that a particular car is affordable or correctly priced.
What is the $3,000 rule for cars?
The $3,000 rule has no single official definition. People may use the phrase to describe a personal limit for repair spending, a minimum cash reserve, or a threshold for deciding whether an older car remains economical. Because the meaning varies, it cannot guarantee that a purchase is sound.
Evaluate any version against repair risk and total ownership cost. Include likely maintenance, tires, brakes, registration, insurance, financing, and the vehicle’s condition. A car that fits the rule but has serious mechanical or structural risk can cost more than a carefully inspected vehicle priced above the informal threshold.
What is the cheapest month to buy a used car?
No single month is guaranteed to be the cheapest for every used-car model, region, or condition. Inventory mix, local demand, vehicle type, and the quality of available examples can matter more than the month itself. Convertibles, sports cars, four-wheel-drive vehicles, and economical cars may respond differently to weather and demand.
Test a local discount by comparing several vehicles with similar age, mileage, engine, drivetrain, equipment, condition, and history. Then compare their out-the-door prices and inspection results. If the apparent saving comes from deferred maintenance, poor history, or added fees, it is not a genuine discount on an equivalent car.
What is the 20% rule when buying a car?
The 20% rule is an informal budgeting guideline, not a lender requirement or a guarantee of affordability. It may refer to a suggested down payment or to keeping car-related costs within a portion of income, but interpretations differ.
Before applying it, account for insurance, maintenance, taxes, registration, fees, interest, and likely repairs. A payment that fits a percentage-based guideline can still be expensive if the APR is high or the loan term is long. Use the rule as a starting point, then confirm affordability through the full transaction and ownership cost.